Key takeaways
- Sequence-of-returns risk is the real killer: the same average return can lead to very different outcomes when you are withdrawing. Design for a bad first five years.
- Build a floor with a 12–24 month cash bridge so you aren’t forced to sell after a fall. Refill from income and rebalancing, not panic sales.
- Use guardrails (Guyton-Klinger style) instead of a fixed “x percent plus inflation”; adjust only when you breach pre-set bands.
- Map currency deliberately: most GCC spending is effectively USD/AED; the dirham is pegged to the US dollar, so USD assets are a natural hedge for AED expenses.
- Keep fees lean; in decumulation, a 1 percent drag both lowers returns and raises your effective withdrawal rate.
- Stress test your plan against: a 30 percent year-one equity drop, a low-return decade, a 15 percent FX swing, and a 0.5–1.0 percent fee increase.
The problem to solve
A 30% equity fall in your first year of retirement is survivable if you design the plan for it. The real danger is not volatility itself but the order in which returns arrive. This is sequence-of-returns risk: identical average returns can produce very different outcomes once you are drawing an income. Vanguard and others have shown how early negative returns combined with withdrawals erode capital faster than most investors expect.
Featured snippet target: What is sequence-of-returns risk?
Sequence risk is the danger that poor market returns occur early in retirement when you are withdrawing from your portfolio, so each withdrawal crystallises losses and leaves less capital to recover later, even if the long-run average return is the same.
A plain-English sequence comparison

Two retirees each average 5% a year over 20 years and both start with £1,000,000, taking £45,000 in year one, uprated by 2.5% annually. The only difference is the order of returns.
Same average, very different results because in Path A withdrawals lock in early losses. This is why we plan for the bad sequence up front.
The four building blocks of resilience
1) Build a floor you can live on
Ring-fence the first 12–24 months of planned spending in cash and high-quality short-duration bonds. For a Dubai household spending about AED 30,000 per month, that is AED 360,000 to AED 720,000 in a cash bridge. Hold this in AED or USD cash and short bonds to minimise price volatility and conversion friction.
When to refill: Top back to 12 months once markets have recovered to within 10% of the previous high, or; refill quarterly from dividends, coupons and any rebalancing sales that occur above target weights. This “cash bridge” stops you selling equities after a fall, a key mitigant highlighted in retirement literature.
2) Use guardrails rather than a fixed withdrawal
The Guyton-Klinger rules are the best-known guardrail framework. In short: set an initial withdrawal, then only lift or cut it if your portfolio breaches pre-set bands, and skip inflation increases after down years. The original research and subsequent updates show higher failure resistance than a rigid “x % plus inflation” rule.
A simple floor-and-ceiling variant you can implement:
- Initial withdrawal: 4.5 % of invested assets.
- Inflation rule: give yourself the full CPI uplift only after positive return years; otherwise freeze in nominal terms.
- Guardrails: if current withdrawal rate drifts above 5.4 percent (+20 percent band) cut next year’s income by 10 percent; if it falls below 3.6 percent (−20 percent band) raise income by 10 percent.
- Capital preservation rule: if the portfolio drops more than 20 percent from a recent high, suspend inflation rises and cap discretionary lump sums until the portfolio recovers within 10 percent of its prior peak.
Worked example (with a 30 percent year-one shock):
- Start: £1,000,000 invested; initial withdrawal £45,000.
- Year 1 market: −30 percent on equities; diversified portfolio ends down −18 percent overall after bonds and cash help. End-year value ≈ £820,000 after taking income.
- Guardrail test: £45,000 ÷ £820,000 = 5.49 percent. That exceeds the 5.4 percent ceiling, so next year’s income is cut by 10 percent to £40,500 and no inflation uplift is applied.
- Year 2 market: +7 percent; portfolio ends ≈ £836,000 after £40,500 income. Withdrawal rate now 4.85 percent, back inside the rails.
- Year 3 market: +9 percent; allow a partial inflation catch-up if the rate remains inside the rails.
This is how an income plan keeps you invested without ignoring reality.
Guardrail rules summary
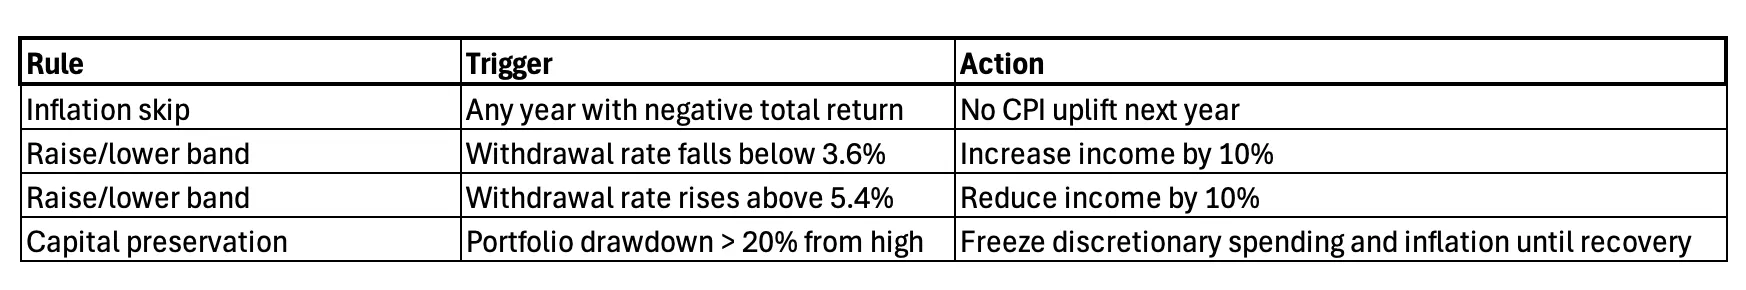
Sources for the method and parameters: Guyton & Klinger; critiques and parameter ranges in later analysis.
3) Rebalance to rules
Pre-set ranges keep emotions out. For example: 60/40 target with a ±5 percentage-point band. If equities fall to 54 percent or lower, rebalance using bond and cash proceeds. This harvests volatility and replenishes risk assets precisely when they are cheap, one of the key mitigants of sequence risk.
4) Map and manage currency across GBP, USD and AED
Most Middle East expenses are in AED. The dirham is closely pegged to the US dollar, and the Central Bank of the UAE operates to maintain USD/AED parity around 3.672–3.673. That makes USD assets a good natural hedge for AED spending, while GBP assets introduce currency risk that you should decide whether to keep or hedge.
Practical options:
- Natural hedging: hold 2–3 years of expected AED spending in USD cash and short bonds; use a USD money-market or short-term Treasury fund for the bridge.
- Staged FX conversions: convert GBP to USD/AED quarterly, not all at once.
- Income matching: direct GBP dividends or pension payments into GBP for UK costs, and use USD sources for life in the Gulf.
- Explicit hedging for GBP exposure: if a large slice of your portfolio is GBP-denominated but you spend in AED, consider GBPUSD hedged share classes or forward contracts within your platform, noting costs and collateral. Institutional and academic work shows that many investors hedge a material portion of foreign currency risk; you should adopt a clear policy rather than drift.
Pulling it together: a GCC-ready drawdown blueprint
- Define spending: essential vs discretionary, converted to AED for the next 24 months.
- Fund the floor: 12–24 months in AED or USD cash and short bonds.
- Set guardrails: start around 4.5 percent; use 20 percent bands with 10 percent adjustments; skip inflation after down years. Tune parameters to your risk capacity.
- Rebalance mechanically: 60/40 with ±5 percentage-point bands is a good starting point.
- Map currency explicitly: decide how much GBP risk to keep; align USD holdings with AED spending; stage conversions.
- Minimise costs: prefer broad, low-cost funds and transparent platforms; monitor total expense ratio and advice fees annually.
- Document NT-code steps if relevant to private pensions; coordinate with your SIPP or scheme payer using HMRC’s DT-Individual guidance.
- Run the stress suite annually or after big life changes.
FAQs
Is a 4 percent “safe withdrawal rate” still valid for UK expats? It depends on fees, asset mix, inflation, sequence risk and currency. Guardrails with a cash bridge are more robust than a fixed inflation-linked rule, especially in low-yield regimes. See the Guyton-Klinger framework and critiques for parameter ranges.
How big should my cash bridge be? Twelve months is a minimum; 18–24 months is prudent for new retirees or those with concentrated equity risk. Refill mechanically from income and rebalancing, not from panic sales.
Should I hold AED directly or just USD? For day-to-day spending, AED balances are fine. Given the long-standing USD/AED peg maintained by the Central Bank of the UAE, USD holdings function as a practical hedge for AED expenses. Still, maintain working-capital AED for bills and use USD instruments for the larger bridge.
Sources










